


What Is the $1,000 a Month Rule for Retirement? A Simple Guide for Late Starters
Updated: 2 days ago
If you've searched online for retirement advice, you've probably come across the "$1,000 a month rule."
It sounds simple.
Save a certain amount to withdraw $1,000 every month in retirement, and you'll be ready for retirement.
The problem?
It's not a rule.
It's a guideline.
If you are starting retirement planning in your 40s, 50s, or 60s, understanding what this guideline includes and leaves out matters more than memorizing a number.
What is the $1,000 a Month Rule for Retirement?
The "$1,000 a month rule" suggests estimating how much you'll need to save for every $1,000 of monthly income you want in retirement.
The confusion starts because there isn't one version of the rule.
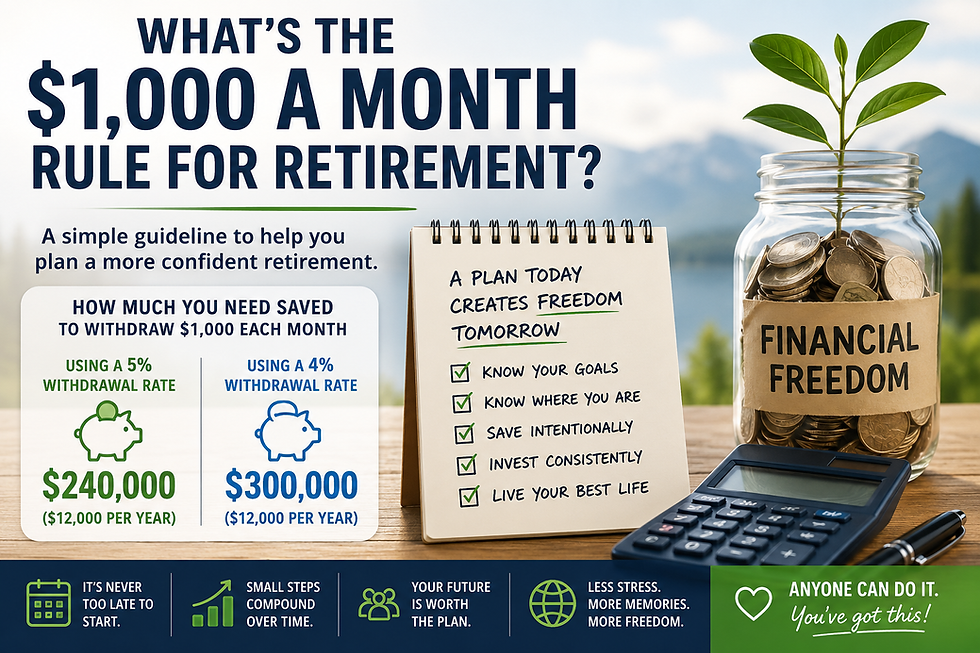
Some articles assume you'll withdraw 5% of your investments each year. Under that assumption, you'll need about $240,000 invested to generate $1,000 per month, or $12,000 per year.
Personally, I don't use a 5% withdrawal rate when helping friends and family build retirement plans.
I use the more conservative 4% rule as my starting point.
Using the 4% rule, you'd need approximately $300,000 invested to generate the same $1,000 per month.
Here's the difference.
Monthly Retirement Income | Using a 5% Withdrawal Rate | Using a 4% Withdrawal Rate |
$1,000 | $240,000 | $300,000 |
$2,000 | $480,000 | $600,000 |
$3,000 | $720,000 | $900,000 |
$4,000 | $960,000 | $1.2 Million |
$5,000 | $1.2 Million | $1.5 Million |
Neither number is right for everyone.
They are planning tools.
Your retirement age, taxes, healthcare costs, inflation, investment returns, and lifestyle all influence how much you'll ultimately need.
The goal isn't finding the perfect rule.
The goal is creating a retirement plan that fits your life.
Why I Prefer the 4% Rule
When I sit down with someone to help estimate their retirement number, I start with the 4% rule.
Why?
I use 4% as an initial planning assumption, not a promise of safety. A lower starting withdrawal requires more savings, and the result still depends on investment returns, retirement length, taxes, and spending.
The arithmetic here estimates an initial annual withdrawal. It does not demonstrate how long a portfolio will last. A strategy which adjusts a starting dollar withdrawal for inflation also differs from withdrawing a fixed percentage of the remaining balance each year.
It's still only a guideline.
If you plan to retire early, travel extensively, or expect significant healthcare expenses, your number may need to be higher.
If you expect a pension, substantial Social Security benefits, or other income sources, your investments may not need to provide your entire retirement income.
Remember, retirement planning isn't about following someone else's formula.
It's about building a plan around your goals.
My Wake Up Call
I didn't become interested in financial independence until I turned 50.
My wife and I were earning more than $130,000 a year, yet buying a new set of tires for my car drained nearly all of our savings.
The bill was about $900.
I remember asking my wife, "How are we making six figures and still only $1,000 away from going broke?"
That moment changed everything.
I started searching for answers.
Those searches led me to the BiggerPockets Money Podcast and eventually to The Simple Path to Wealth by JL Collins.
One lesson changed how I viewed money forever.
Investing doesn't have to be complicated.
It starts with your first investment.
Since then, we've paid off more than $380,000 in debt, built a rental property portfolio, and grown our net worth to more than $580,000.
More importantly, we've stopped living paycheck to paycheck and started spending with purpose.
Why the $1,000 Rule Falls Short
This guideline leaves out several important pieces of your retirement plan.
Inflation
A thousand dollars today won't buy what it buys 20 years from now.
Your retirement income needs to grow along with the cost of living.
Taxes
Many retirees forget taxes.
Withdrawals from Traditional IRAs and 401(k)s are generally taxed as ordinary income. Brokerage accounts also create tax considerations.
Understanding your future tax picture is part of retirement planning.
Healthcare
Healthcare costs typically increase during retirement. Ignoring those expenses often leaves retirees short.
Your Retirement Lifestyle
This guideline assumes you're average. Most people aren't. Some people dream of traveling every year.
Others want to help grandchildren with college.
Some want to donate generously.
Others simply want enough income to enjoy dinner out without checking their bank account first.
Your retirement should reflect your goals, not someone else's average.
How I Help People Calculate Their Retirement Number
One of the first questions I ask is simple.
Where are you trying to go?
Recently, I helped a friend in her mid 40s who had recently gone through a divorce.
She had two teenage children and believed she'd never retire.
For example, if investments must supply $50,000 in the first year, dividing by a 4% starting withdrawal assumption gives $1.25 million. First account for Social Security, pensions, other income, and taxes to estimate the amount the portfolio must provide.
She immediately felt defeated.
Instead of stopping there, we looked at her complete financial picture.
We reviewed:
Current spending.
Home equity.
Retirement accounts.
Taxes.
Healthcare options.
Estimated Social Security benefits.
List retirement accounts, brokerage accounts, and other assets separately from debts. Home equity contributes to net worth, but it is not automatically available to fund withdrawals. Count it as retirement cash flow only with a specific plan to access it and an allowance for costs.
Next we:
Eliminated unused subscriptions.
Improved her 401(k) investments.
Opened a Roth IRA.
Opened a brokerage account.
Automated monthly investing.
Today she has a roadmap instead of fear.
That's what retirement planning should provide.
Four Steps to Get Started Today
If you're getting a late start, don't panic.
Start here.
1. Know Your Destination
Estimate how much you'll spend each year in retirement.
Without a destination, every number feels overwhelming.
2. Eliminate Consumer Debt
Interest works against you.
Every dollar going toward high interest debt isn't building your future.
3. Capture Every Employer Match
If your employer offers a 401(k) match, contribute enough to receive the full amount.
It's one of the best returns you'll ever earn.
4. Automate Your Investing
Review retirement account options available to you. IRA contribution eligibility and deductibility depend on earned income and other rules, so check the applicable requirements before contributing.
Set up automatic monthly deposits.
Choose an investment mix suited to your timeline and ability to tolerate losses. A broad stock index fund provides stock exposure but does not, by itself, create a balanced mix of stocks, bonds, and cash.
Simple beats complicated.
One Retirement Myth That Costs People Years
"I'll work longer." I hear it all the time.
The reality is different.
Health problems.
Burnout.
Layoffs.
Corporate restructuring.
Life doesn't always cooperate with our plans.
Stress-test your plan for an earlier-than-expected retirement, job loss, healthcare costs, inflation, and poor market returns. A target date is a planning assumption, not a guarantee.
What Financial Independence Means to Me
My goal isn't luxury.
It's freedom.
Freedom to take one big trip every year.
Freedom to stay debt free except for our 3% mortgage.
Freedom to enjoy dinner with my wife and friends without worrying about the bill.
Freedom to spend time with family.
Freedom to spoil future grandchildren.
Freedom to teach others what I wish I'd learned decades ago.
That's what retirement is really about.
Frequently Asked Questions
Is the $1,000 a month rule accurate?
It's a useful starting estimate, but it doesn't account for taxes, inflation, healthcare, Social Security, or your personal retirement goals.
Is the 4% rule better?
I use the 4% rule as a planning guide because it helps estimate your retirement savings goal based on annual spending. Like every rule of thumb, it should be adjusted for your personal situation.
What if I'm already in my 50s?
You're not too late.
Review your spending, eliminate consumer debt, maximize retirement contributions, automate investing, and build a realistic plan.
Many people have 10 to 20 years before retirement and still have time to make meaningful progress.
Final Thoughts
The biggest mistake isn't starting late.
It's believing you're too late to start.
I didn't begin my financial independence journey until age 50.
Today I'm in a completely different financial position because I stopped hoping and started planning.
The $1,000 a month guideline isn't your retirement plan.
It's simply the first step toward building one.
It's never too late to start preparing for retirement.
Anyone can do it.
Updated October 10, 2026. General financial education; examples are illustrative and individual circumstances differ.


Comments